Employer-Funded Vending: Set a Budget Review Trigger Before Launch
An employer-funded vending arrangement needs a way to notice when spending should be reviewed. Agree that point before launch rather than waiting for an unexpected invoice. A review trigger is a prompt for the responsible people to examine the position; it should not be described as an automatic spending cap unless that capability is actually confirmed.
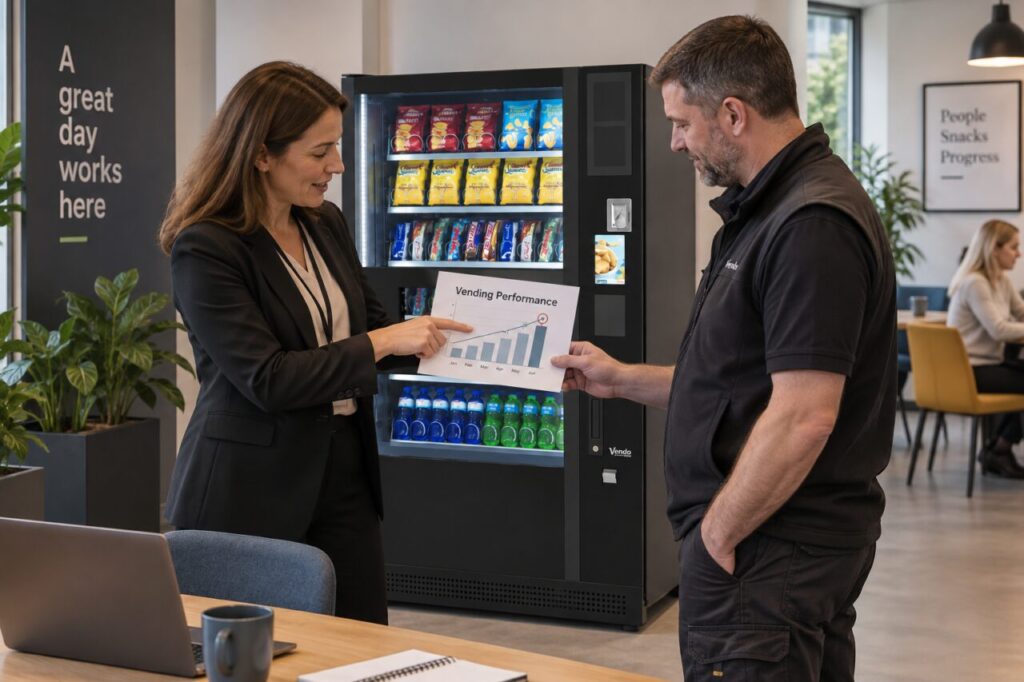
The trigger can be managed through the reporting process available in your arrangement. It does not require an invented dashboard or a promised automated alert. Ask what information the operator can provide, how often it becomes available and who in the organisation will review it alongside the agreed budget assumptions.
Define what the budget covers
Write down the scope of the employer’s contribution before deciding when to review it. Clarify the eligible audience, products and period through the agreed proposal. Keep service charges or other costs distinct where the arrangement requires that distinction, so the person reviewing the figures understands what is included in the total being considered.
Avoid using a vague statement such as free vending for all staff when the actual arrangement has conditions. Confirm those conditions with the relevant parties and communicate them accurately. The initial budget should reflect the agreed service, not a broader promise made informally before the operator has confirmed how the arrangement will work.
Choose a review point that supports a decision
The appropriate review point depends on the employer’s budget process and the available reporting. It might be a regular scheduled review or an agreed spending threshold. Let the responsible budget owner decide what is useful, and record whether the figure is provisional, accrued or invoiced rather than treating unlike measures as interchangeable.
Allow for the time needed to receive and review the information. A report delivered after a period ends cannot provide a real-time control during that period. Ask the operator to explain the timing clearly and choose a process that the organisation can actually maintain with the evidence available through the agreed service.
Assign the response to the trigger
Identify who receives the information and who can decide what happens next. The site host may collect feedback while finance owns the budget. Make that distinction explicit so a review request is not left unanswered because each person assumes the other has authority to change the range, funding or service arrangement.
Agree what the first review should examine. Changes in attendance, eligibility, product mix or the reporting period may help explain the figures. Do not jump directly from higher spending to a conclusion about misuse. Start with the scope and the records, and involve the operator where a question requires service-specific information.
Communicate confirmed changes carefully
If the review leads to a proposed change, confirm it through the appropriate approval and supplier process before informing staff. Give a clear effective date where one is agreed. Avoid announcing that a benefit has ended or that a limit is active while the operational details are still being discussed between the parties.
Keep the decision and supporting information with the service record. At the next review, check whether the change addressed the original concern without creating a different access or communication problem. A budget process is more useful when it records what was decided and why, rather than collecting figures without an owner or follow-up.
When considering workplace vending options, discuss both customer experience and budget oversight. The visitor and contractor guide helps clarify the audience, which is one important input when deciding what the employer-funded arrangement is intended to cover.
Discuss an appropriate workplace arrangement with the audience, reporting needs and budget process explained.