Percentage Vending Subsidies: Agree How Rounding Works
A percentage vending subsidy sounds simple until the calculation produces part of a cent. Before launch, ask the provider how the installed scheme converts the percentage into the employee’s payable amount and the employer’s contribution. Agree the rule in the scheme documentation and test it with realistic prices. A small unexplained difference can otherwise create repeated questions at the machine and in the monthly report.
Define what the percentage applies to
Start with the products and prices covered by the scheme. Confirm whether the contribution applies to every eligible purchase or only specified categories or occasions. Our fully managed service page includes percentage contributions among the available subsidy approaches. The detailed calculation still needs to be agreed for the actual scheme; a general example is not a complete operating rule.
Ask how any other offer or allowance interacts with the percentage, if such a combination is proposed. Do not assume discounts can be combined or applied in whichever order produces the lowest amount. Record the supported arrangement before advertising it. Staff need one understandable explanation, and finance needs a calculation that corresponds with the report supplied by the provider.
Work through an awkward example
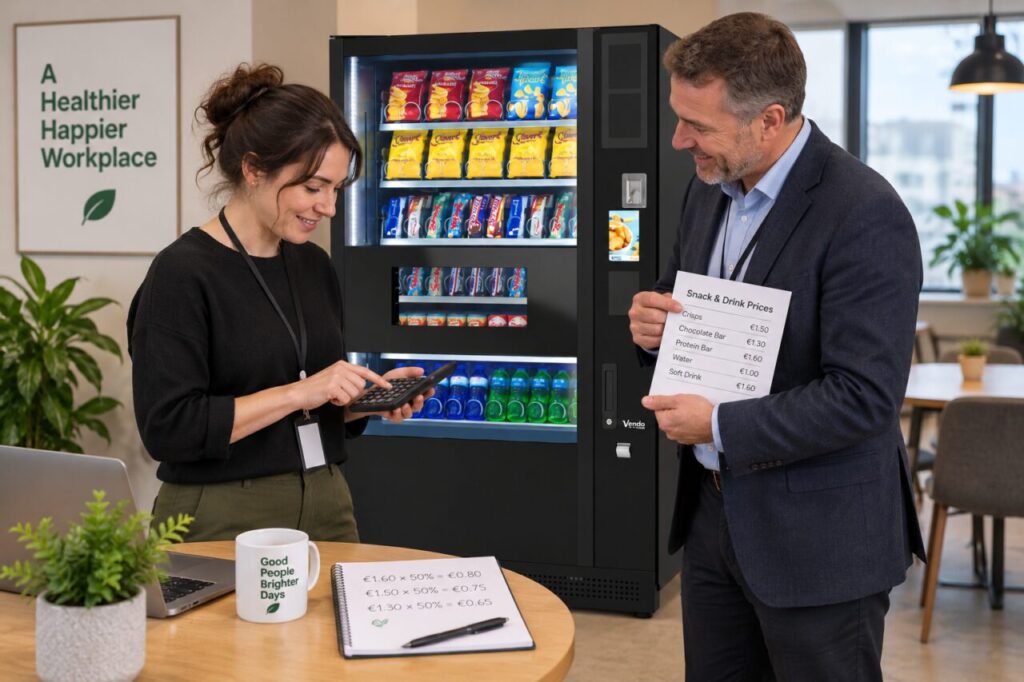
For illustration only, a hypothetical product priced at €1.95 with a 50% contribution produces an exact half of €0.975. That arithmetic does not tell you whether the installed scheme will charge the employee €0.97 or €0.98, or how it records the employer portion. Ask the provider to demonstrate the agreed result rather than selecting a rounding direction locally.
Use several sample prices, including one that divides cleanly and one that does not. Make clear that these are test amounts, not advertised product prices or promises about the site’s range. Ask whether the calculation is applied per item or in another supported way. Keep the explanation aligned with the actual purchase process rather than assuming the machine supports a combined basket.
Reconcile the customer charge and report
Arrange an authorised test and record the displayed employee amount, completed charge and employer contribution shown in the relevant reporting process. Ask how those values reconcile to the agreed selling price. If a difference remains unexplained, resolve it before telling staff the scheme is ready. A correct percentage in a settings screen is not enough if the resulting transaction or report is unclear.
Keep test activity distinguishable from ordinary employee use. Agree who performs the test and how any test stock or payment is recorded. Do not ask staff to make repeated personal purchases to discover the calculation by trial and error. The provider should be able to explain the supported rule and the evidence needed to confirm that the installed arrangement follows it.
Explain the rule without overloading staff
Give users a short description of the contribution and tell them where to check the amount before completing a purchase. If rounding can affect the final cent, explain it accurately in the scheme information. Avoid an absolute statement that employees always pay an exact mathematical fraction when the supported calculation necessarily uses whole-cent amounts. Keep detailed reconciliation instructions with the administrator.
Review the examples when prices or scheme rules change. Update staff information and finance records together so an old illustration does not become misleading. Consider the subsidy alongside the actual workplace product range, rather than treating funding as a substitute for useful choices. The aim is a benefit that people understand and an employer report that can be checked without guesswork.
Contact our team to discuss a workplace subsidy and its setup requirements.
Related guidance: Staff Vending Allowances: Explain Items, Credit and Entitlements Clearly.