
A Vending Break-Even Calculation Gives a Fraction: Round Up the Required Sales
A vending break-even calculation can produce a fraction of a sale. If the question is how many whole sales are needed to cover the stated costs, round that result upwards. Rounding to the nearest whole number can leave a small shortfall, even though the displayed answer looks tidy.
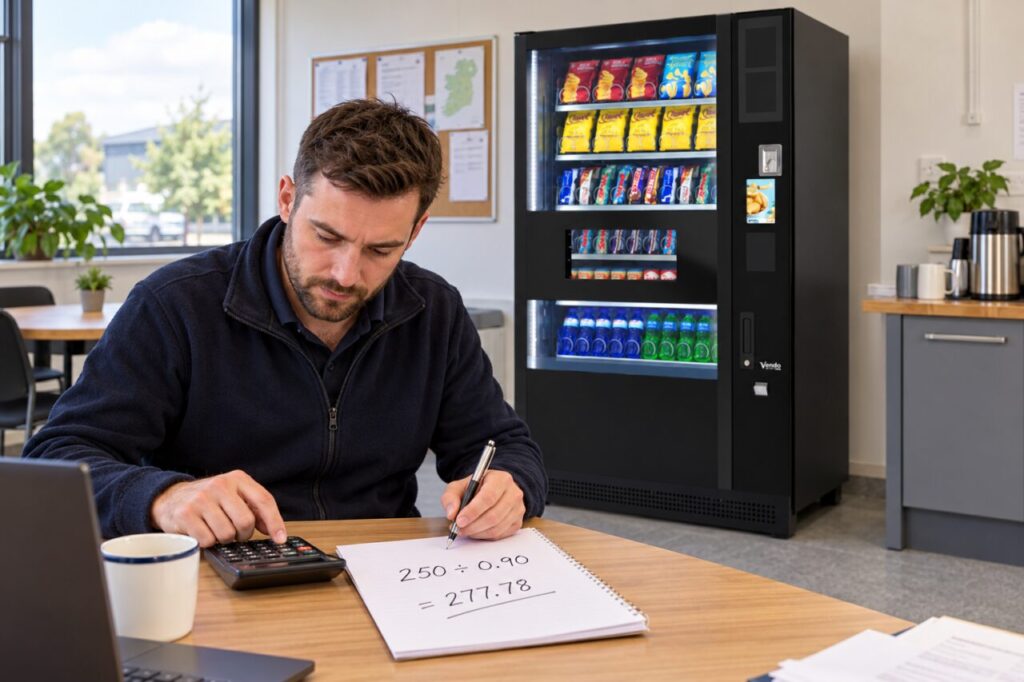
The calculation is only as useful as its assumptions. Use a positive contribution per sale, a clearly defined cost period and a consistent revenue and cost basis. The example below is hypothetical and simplified; it does not predict sales or represent the prices and costs of a particular vending service.
Calculate before rounding
Suppose the relevant fixed costs for the period are EUR250 and each sale contributes EUR0.90 after the variable costs included in the model. Dividing 250 by 0.90 gives approximately 277.78 sales. Because a completed sale is counted as a whole unit, the minimum whole number meeting that threshold is 278.
Check both sides of the boundary. At 277 sales, contribution is EUR249.30, which is EUR0.70 below the stated fixed costs. At 278 sales, contribution is EUR250.20, which is EUR0.20 above them. This simple multiplication check makes the reason for rounding upwards visible instead of treating it as a spreadsheet convention.
Keep the period consistent
If EUR250 represents a month, the answer is a monthly total under the assumptions. Do not describe it as a weekly or daily target without another calculation. When dividing across operating days, use the number of relevant open days and explain that actual sales may vary substantially between them.
Avoid rounding several intermediate steps prematurely. A daily target rounded up and multiplied back across the month can produce a different total from the original monthly threshold. That may be a deliberate planning buffer, but label it accordingly. Keep the precise calculation available and distinguish the mathematical boundary from the practical target you choose to manage.
Check what one sale represents
The example assumes the same contribution for every sale. A mixed vending range needs an appropriate estimate of average contribution based on the expected product mix. A threshold calculated using only the highest-contribution product will be misleading if customers buy a different balance of snacks and drinks.
Revisit the calculation when selling prices, purchase costs or relevant charges change. If contribution is zero or negative, this positive-contribution formula does not produce a useful finite sales threshold for covering positive fixed costs. Investigate that position directly rather than forcing the spreadsheet to display a reassuring target.
Use the result as a planning input
Compare the whole-sale threshold with observed demand and the site’s operating conditions. Reaching the arithmetic threshold is not guaranteed by installing equipment or increasing the available stock. Keep the demand estimate separate and explain its evidence, including any uncertainty about attendance, opening hours or the range being offered.
Record the cost figure, contribution assumption, unrounded answer and rounded whole-sale requirement together. Add any chosen buffer as a separate decision, with a reason and review date. This gives the operator a calculation that can be checked and updated: the threshold answers the stated cost question, while the wider plan addresses whether those sales are realistically achievable.
For help matching the service to your site, explore Vending-Machines.ie or send an enquiry describing your requirements.
Related guidance: Vending Break-Even Targets: Count Items Separately from Payment Transactions.