A Vending Sales Report Shows a Negative Day: Trace Adjustments Before Calling It a Loss
A negative figure in a vending sales report needs investigation before it is described as a trading loss. The report may include refunds, corrections or adjustments related to earlier purchases. Start by reading the field definition and the underlying entries. A daily net-sales total and a profit calculation answer different questions.
Keep the original report and note when it was generated. Check the date range, time zone and whether the system groups activity by sale date, adjustment date or another basis. Do not delete the negative line merely to make a chart look normal. It may be a valid result of the report’s calculation method.
Find the entries behind the total
Review the transaction detail available through the authorised reporting system. Identify the positive sales and negative adjustments included in the day. Keep the original references so each adjustment can be connected to the relevant purchase where supported. Ask the provider to explain unfamiliar transaction types instead of assigning your own meaning to a minus sign.
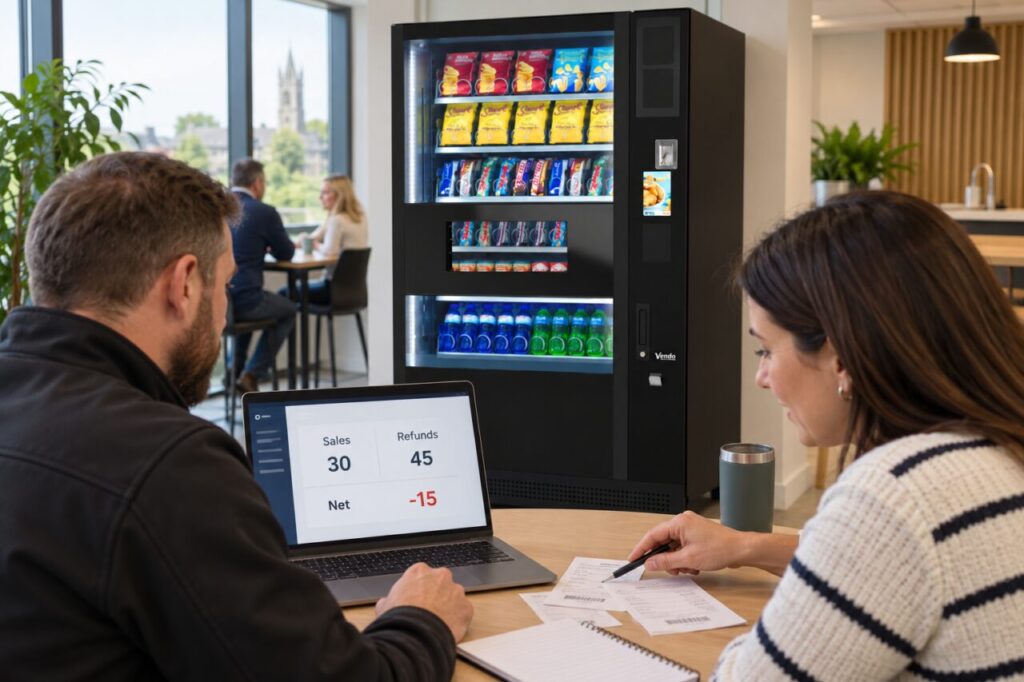
For example, a hypothetical day with €30 of recorded sales and €45 of refunds included in the same daily calculation would show net sales of minus €15. That arithmetic does not establish the day’s profit or cash movement. The refunds might relate to earlier sales, and the report may not include all costs or settlement activity.
Check timing and duplication
Determine whether the adjustments belong to purchases from another period. If so, explain that timing in the management report. Do not move entries between dates in the source system merely to smooth the trend. Any correction should follow the provider’s and business’s approved process, with an audit trail that preserves what changed and why.
Check whether a refund or correction has appeared twice in an exported analysis. Duplicate imports can distort the total even when the underlying platform is correct. Compare references and export coverage before removing anything. Two similar amounts are not automatically duplicates; separate customers can make purchases or receive adjustments of the same value.
Separate sales, settlement and profit
Ask which measure you are reviewing. Net sales, money paid into a bank account and operating profit should not be used as interchangeable labels. When assessing a vending machine business, keep the reporting definitions visible so an unusual daily number does not lead to an unsupported conclusion about the site’s viability.
Use the appropriate accountant or reporting provider for questions about formal treatment. This checklist concerns understanding an operational report, not deciding accounting entries. Avoid treating a negative sales day as evidence that products should be removed or prices changed until the underlying activity and the relevant costs have been established.
Explain the finding with the original total
Once the cause is understood, annotate the report with the relevant facts: the adjustments included, their timing and any confirmed correction. Retain the original figure and show any management comparison separately. If the cause remains unresolved, say so and record who is investigating it. An uncertain result should not be presented as a confirmed equipment or trading problem.
Review a suitable period alongside the individual day, using consistent definitions. A single adjustment-heavy day may look very different from the broader trading pattern. The useful outcome is a traceable explanation that lets the operator distinguish ordinary customer activity from reporting effects, while leaving the financial records accurate and the next business decision properly informed.
Related guidance: Vending Refunds in a Later Report: Keep the Original Sale Traceable.
For help assessing your site, contact Vending-Machines.ie.