
A Staff Member Pays for a Vending Test: Agree the Reimbursement Record
During a supervised vending check, a site employee may be asked to make a purchase using their own payment method. Before anyone pays, agree whether this is a normal personal purchase or a test expense that somebody will reimburse. That small distinction prevents an avoidable dispute after the machine has been handed over.
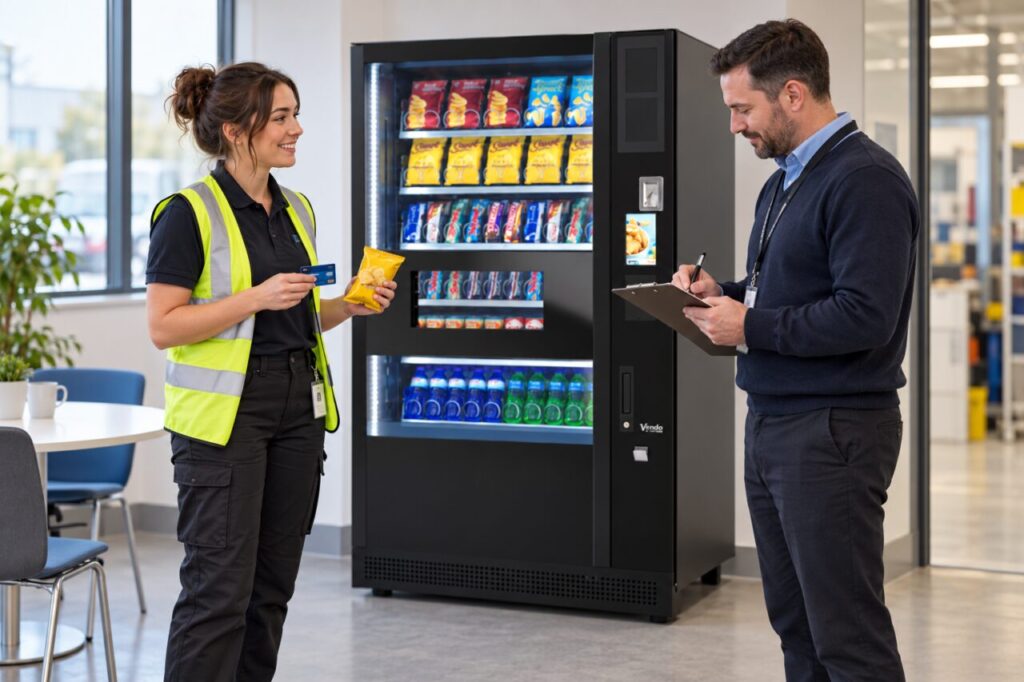
There is no universal reimbursement arrangement for every installation or service visit. The employer, operator and supplier may have different responsibilities. Ask the person authorised to arrange the test to explain the process, including what evidence is needed and who will receive the request.
Agree the purpose before paying
Write down the task being checked, such as confirming that the agreed selection can be purchased and collected at the final location. Confirm who approved the test and whether the employee is expected to keep the item, return it through an agreed process or pass it to the person supervising.
If the employee is uncomfortable using a personal card, raise that before the demonstration begins. Ask the responsible party to arrange another approved method. Do not promise that a charge will automatically reverse or that a supplier will reimburse it unless that has been confirmed for this particular transaction.
Capture only the evidence needed
Record the date, approximate time, machine identity, selection and amount shown for the test. Keep any receipt or confirmation supplied through the normal payment process. If no receipt is available, ask what alternative record the organisation accepts rather than repeatedly buying products to obtain a different result.
Avoid circulating a full bank statement, complete card number or unrelated transactions. Where a payment query requires additional details, use the authorised support route and provide only what is requested. A shared commissioning checklist should not become a store of employees’ private financial information.
Separate reimbursement from a payment fault
A successful purchase awaiting an agreed expense repayment is different from a payment problem. Describe the actual situation. If the product was received and the transaction was expected, the outstanding issue may be the internal repayment process. If the outcome was unclear, report that uncertainty to the appropriate support contact.
Do not submit the same amount simultaneously as an employer expense and an operator refund without explaining the circumstances. That can create conflicting records or an unintended duplicate payment. Give each request a reference and tell the relevant contact if another party has already resolved the amount.
Close the test and the expense separately
The equipment check can have one outcome and the repayment another. For example, the supervisor may confirm that the test purchase succeeded while the expense remains awaiting approval. Record both states. Avoid holding the technical record open merely because an administrative step is pending, or closing the expense because the machine works.
When the agreed repayment arrives, match the amount to the original test and record who settled it. If several employees participated, keep their purchases distinguishable. An aggregate note saying five tests completed is not enough to establish who paid for each item or which person still needs a response.
For future visits, agree a repeatable test-payment arrangement in advance. Include the authorised payer, evidence requirements and contact for unresolved expenses in the handover checklist. This keeps the demonstration focused on the equipment while treating the employee’s money as a separate, explicit responsibility.
Related guidance: read Vending Test Purchases: Separate Commissioning Activity from Customer Demand for the connected question.
Include any site restrictions on test purchases in your enquiry.