A Vending Supplier Offers a Cash Discount: Compare the Saving with the Payment Timing
An early-payment discount on vending supplies can reduce an invoice amount, but it also changes when cash leaves the business. Compare the saving with the actual payment deadline and other commitments before deciding. The offer should be reviewed as a specific supplier term, not treated as an automatic reason to bring every payment forward.
First confirm what the supplier means by the discount. Check the eligible invoice or items, the deadline, the payment method and any conditions. Do not assume the phrase cash discount requires physical cash; ask for the agreed method. Keep the written terms with the invoice so the person arranging payment can follow the same basis.
Calculate the stated saving
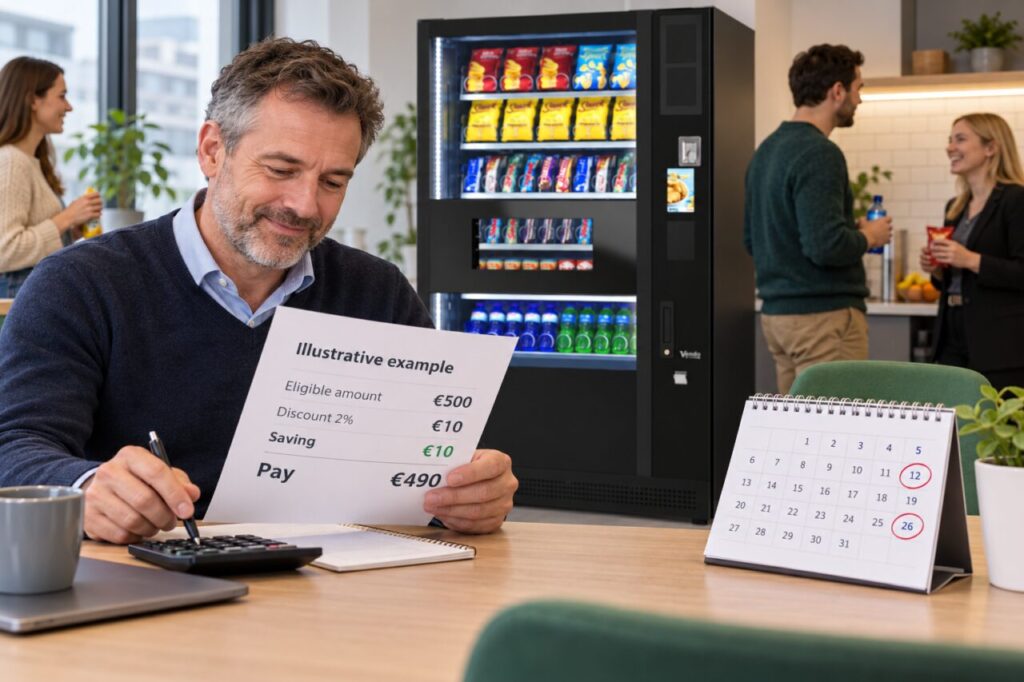
Use the amount to which the discount actually applies. In a simple hypothetical example, a 2% discount on an eligible €500 amount is €10, leaving €490 for that portion. This is an illustration, not a current supplier offer. Tax, delivery and excluded items may require separate treatment according to the invoice and accounting advice.
If the offer applies only to selected goods, do not calculate it on the whole invoice. Ask the supplier to clarify ambiguous wording before recording a saving. Keep the calculation visible and distinguish an available discount from one actually earned by meeting the conditions. An advertised reduction is not yet a confirmed transaction outcome.
Compare the timing with cash commitments
Place the proposed earlier payment date beside upcoming stock, service and other business payments. The question is whether taking the discount would leave adequate cash for those commitments. Do not count expected card settlements as available cash until their timing is understood, and do not assume every forecast sale will arrive before the invoice deadline.
Where borrowing or other financing would be needed, compare the real costs and seek appropriate advice. A small invoice reduction may not justify another cost or a missed obligation. Avoid annualising the discount into an impressive return figure without explaining the assumptions; the immediate decision concerns this invoice, this deadline and the business’s actual cash position.
Keep the purchase decision separate
An early-payment offer does not make unnecessary stock useful. Confirm that the goods and quantities are appropriate independently of the discount. Check the order and delivery records before paying, and resolve material discrepancies through the supplier’s normal process. Do not allow a short deadline to replace ordinary checks on what was ordered and received.
When estimating vending operating costs, show discounts consistently and avoid counting the same saving twice. The purchase record, payment and any supplier adjustment should agree. Your accountant can advise on the appropriate treatment for the business; a management worksheet should not silently substitute its own accounting or tax assumptions.
Confirm the outcome in the records
Use the authorised payment process and retain evidence of the amount and date. If timing is close to the deadline, ask the supplier which date determines eligibility rather than assuming that initiating payment is sufficient. Do not change payment details from an unverified message simply because it refers to an urgent discount opportunity.
After payment, check that the supplier has applied the agreed reduction and that any remaining balance is understood. If the discount was not earned, correct the forecast rather than carrying an unrealised saving forward. A useful review balances the confirmed euro benefit, the cash timing and the ordinary purchasing controls, without assuming that paying sooner is always the better choice.
Related guidance: Vending Card Payouts Arrive After the Weekend: Plan the Stock Payment Gap.
For help assessing your site, contact Vending-Machines.ie.