A Vending Budget Includes Your Own Labour: Keep Cash Costs and Time Separate
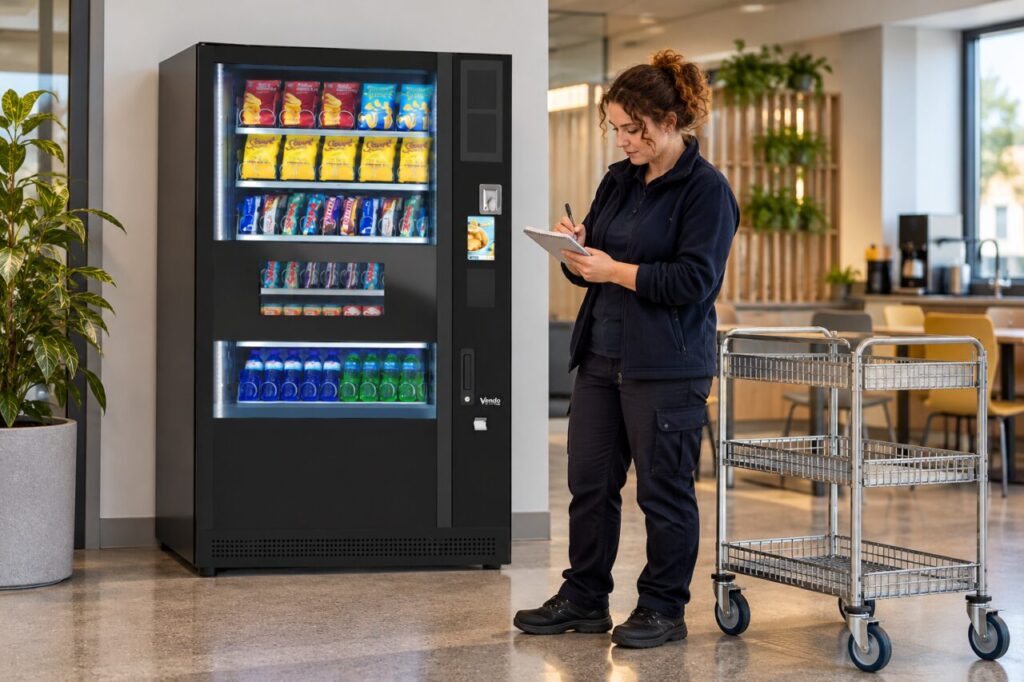
A vending owner may refill machines, order stock and answer customer queries without paying themselves a separate hourly wage for each task. That does not make the time irrelevant. When preparing a budget, show cash expenditure and the owner’s working time separately so the business can be assessed from both perspectives.
This is a management-planning exercise, not advice on payroll, tax or accounting treatment. Use your accountant’s guidance for formal records. The practical question is whether the operation produces an acceptable result for the cash committed and the work required, including tasks that are easy to overlook.
Record the work that actually happens
Include ordering, receiving stock, preparing the route, travelling, gaining access, refilling, reconciling records and dealing with support queries. Avoid measuring only the minutes spent at the open machine. A small refill can still require preparation and administration before and after the site visit.
Keep a short time record over a representative period, noting unusual delays separately. When reviewing vending running costs, distinguish observed time from an early estimate. The purpose is to understand the workload, not create a level of precision that the record cannot support.
Keep cash payments visible in their own column
Record actual cash costs using the relevant invoices and payment records. Do not add an assumed owner-time value to the bank-spending total and then describe the result as money already paid. Conversely, do not describe a positive cash balance as proof that the owner’s time has been adequately rewarded.
A hypothetical example can make the distinction clear. If a task takes three hours and you use EUR20 per hour purely as a planning assumption, its imputed time value is EUR60. That is not a wage-rate recommendation, a supplier quote or necessarily a payment. Label it as an internal assumption and retain the three-hour observation separately.
Test how the workload changes with the business
Ask which tasks would grow if another machine or site were added. Some work may be shared, such as preparing one combined stock order, while travel and access could increase substantially. Do not assume that doubling sales doubles every task, or that the extra work will be absorbed without affecting the existing route.
Consider what would happen if someone else had to provide cover. Obtain actual quotations or employment advice where relevant rather than treating the owner’s planning rate as a guaranteed replacement cost. The comparison can reveal whether the current operation depends on unpaid availability that would be difficult to replace.
Review the result without mixing the measures
Present a cash view and a time-informed view, explaining what each includes. Use the same period for sales, expenses and working hours. Keep one-off setup effort separate from recurring work where that distinction helps the decision, but do not omit recurring administration simply because it happens at home or between other tasks.
Update the assumptions when the route, service arrangement or owner’s availability changes. A realistic budget should show both the money required and the practical workload behind the result. That makes it easier to decide whether to adjust the operation, obtain support or investigate another site without relying on the misleading idea that personally supplied time has no cost at all.
Related guidance: Adding a Second Vending Site: Check Who Owns the Extra Working Hours.
For help assessing your site, contact Vending-Machines.ie.